Bike Loans Australia Vehicle Lease Repayment Calculator
Explore potential car leasing costs with our Car Lease Calculator. Estimate monthly payments and test different interest rates, lease terms and residual (balloon) amounts to see how these variables may influence your repayments and overall leasing costs.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Car Lease Details:
Important!
Car Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Lease Amortisation Calculator
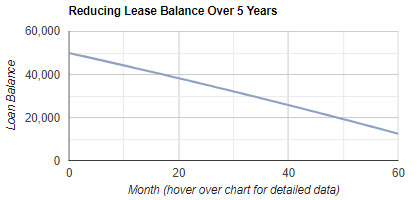
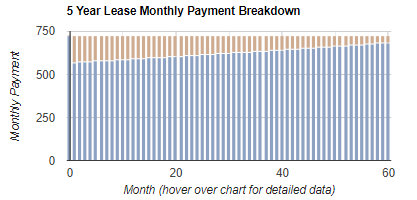
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Vehicle Lease Repayment Calculator
Our Vehicle Lease Repayment Calculator helps you estimate monthly lease repayments for a motor vehicle by modelling three key variables: interest rate, lease term, and the residual or balloon amount payable at the end. It’s important because small changes to any of these inputs can materially affect cash flow, total interest over the term, and the end-of-lease obligation, helping you compare scenarios before you speak with a lender or novated leasing provider.
How to complete the form for the best result:
1. Purchase Price
Enter the total amount you want financed for the vehicle. Include relevant upfront costs you intend to roll into the lease (for example, on-road costs or insurance where applicable). Use whole numbers only (no decimals, commas, or dots).
2. Balloon or Residual Value (percent of purchase price)
Select the residual percentage. A higher residual generally reduces the monthly payment but increases the amount left owing at the end, which can increase overall cost across the term. Choose a residual that matches your intended end-of-lease plan (keep, refinance, or sell).
3. Term of Loan (years)
Choose the number of years. Longer terms usually reduce monthly repayments but can increase total interest paid. Select a term that suits how long you expect to keep the vehicle and your budget tolerance.
4. Interest Rate (per annum)
Select an interest rate to simulate. Use a conservative rate when stress-testing affordability, because your actual rate may differ depending on lender policy and your circumstances.
5. Calculate
Click calculate to generate your estimated monthly lease repayment and amortisation visuals.
How to interpret the results:
1. Monthly repayment estimate: Use this as a budgeting guide and compare scenarios by adjusting term, rate, and residual.
2. Amortisation charts: Review how the balance reduces over time and how much of each payment is interest versus principal; this highlights when interest costs are highest and the impact of a larger residual.
ASIC compliance note: This guide is general information only and does not consider your objectives, financial situation or needs. Consider the full lease contract, fees, taxes, insurance, maintenance, and end-of-lease options before deciding, and consider getting personal advice if needed.
Finding a motorcycle finance deal online can be convenient, but the lowest advertised rate is not always the best overall option. Australian riders should compare loan types, fees, repayment terms, lender credibility and online application requirements before choosing a finance offer. - read more
Motorbike loan eligibility in Australia usually depends on your income, employment, credit history, existing debts, residency, age, deposit, loan type and the bike being financed. This guide explains the common factors lenders consider before you apply. - read more
There's nothing quite like the thrill of the open road, especially when you're riding a motorcycle. The roar of the engine, the rush of wind against your face, and the feeling of absolute freedom are incomparable, turning every journey into an adventure. Owning a motorcycle is not just about transportation; it's a lifestyle choice that speaks to those who love the exhilaration of travel on two wheels. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent gives motorcycle buyers a fresh reason to slow down and check the finance numbers before committing to a bike. The move does not mean every motorbike loan will automatically become more expensive overnight, but it does increase pressure on the broader cost of credit and may influence how lenders price new fixed and variable-rate offers. - read more
Renewed attention on how lenders manage customers in financial difficulty is a timely reminder for Australian riders: a motorbike loan is not just about approval day. It is a commitment that needs to remain manageable if income changes, living costs rise, overtime dries up or unexpected bills land at the worst possible moment. - read more
Fresh motorcycle loan comparison updates are a timely reminder that the lowest advertised interest rate is only part of the finance story. Several lenders continue to promote competitive secured vehicle and motorcycle finance offers, but the rate a rider actually receives will still depend on their credit profile, income, existing debts, loan size, bike age and the lender’s appetite for risk. - read more
Mutual Fund: An investment vehicle made up of a pool of funds collected from many investors for the purpose of investing in securities such as stocks, bonds, money market instruments, and other assets.