Bike Loans Australia Bike Loan Repayment Calculator
Calculate motorcycle loan repayments in seconds with our Bike Loan Calculator. Compare finance options and plan your ride with confidence.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Bike Loan Details:
Important!
Bike Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Bike Loan Amortisation Calculator
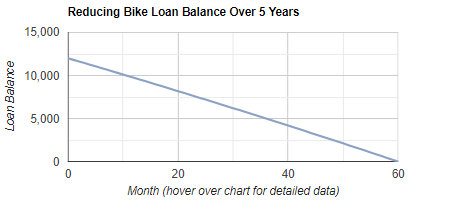
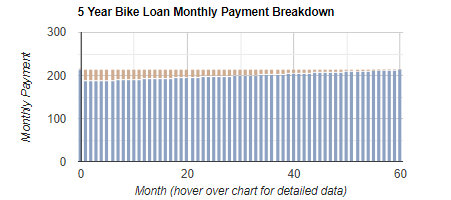
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Bike Loan Repayment Calculator
Our Bike Loan Repayment Calculator is designed to estimate your motorcycle loan repayments in seconds, so you can compare bike finance options and plan your budget before you commit. It is important because small changes to loan size, term length and interest rate can materially change your monthly repayment and the total interest you pay over the life of the loan.
This calculator provides estimates only and is not personal financial advice. Results do not take into account your objectives, financial situation or needs. Interest rates and fees vary by lender and your individual circumstances, and your final rate can only be confirmed after an application is assessed.
How to complete the form for the best result:
1. Purchase Price
Enter the bike purchase price as a whole number (no dots or commas). If you expect to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts in the figure you enter so the estimate better reflects your likely loan amount.
2. Deposit or Trade-in Value (if applicable)
Enter your deposit or trade-in value as a whole number. If you have no deposit, enter 0. A higher deposit generally reduces the amount borrowed and can reduce interest paid over time.
3. Term of Loan (Years)
Select a term between 1 and 7 years. Longer terms typically reduce monthly repayments but can increase the overall cost of the loan due to more interest over time. Choose a term that fits your cash flow, not just the lowest repayment.
4. Interest Rate (% per annum)
Select an interest rate for the simulation. If you are unsure, test a conservative higher rate to see whether repayments remain affordable.
5. Calculate
Click calculate to generate your estimated repayment and amortisation visuals.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a starting point for budgeting, then stress-test by increasing the rate or reducing your deposit to see how sensitive repayments are.
2. Amortisation graphs
Review the loan balance chart to understand how quickly you reduce what you owe, and the interest versus principal chart to see how much of each repayment goes to interest compared with reducing the loan balance over time.
There's nothing quite like the thrill of the open road, especially when you're riding a motorcycle. The roar of the engine, the rush of wind against your face, and the feeling of absolute freedom are incomparable, turning every journey into an adventure. Owning a motorcycle is not just about transportation; it's a lifestyle choice that speaks to those who love the exhilaration of travel on two wheels. - read more
For many, the thrill and freedom that come with owning a motorcycle are unparalleled. Whether you're envisioning leisurely weekend rides through Australia's beautiful landscapes or using it for your daily commute, owning a motorcycle can bring an exciting new dimension to your life. - read more
Motorcycles symbolize freedom and adventure, but to keep the spirit of the ride alive, regular maintenance is a must. Beyond the roar of the engine and the aesthetic appeal, lies a complex machine that requires careful attention to detail. The importance of regular maintenance for motorcycles extends far beyond keeping up appearances; it plays a crucial role in ensuring the safety, performance, and longevity of your cherished two-wheeled companion. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent gives motorcycle buyers a fresh reason to slow down and check the finance numbers before committing to a bike. The move does not mean every motorbike loan will automatically become more expensive overnight, but it does increase pressure on the broader cost of credit and may influence how lenders price new fixed and variable-rate offers. - read more
Renewed attention on how lenders manage customers in financial difficulty is a timely reminder for Australian riders: a motorbike loan is not just about approval day. It is a commitment that needs to remain manageable if income changes, living costs rise, overtime dries up or unexpected bills land at the worst possible moment. - read more
Fresh motorcycle loan comparison updates are a timely reminder that the lowest advertised interest rate is only part of the finance story. Several lenders continue to promote competitive secured vehicle and motorcycle finance offers, but the rate a rider actually receives will still depend on their credit profile, income, existing debts, loan size, bike age and the lender’s appetite for risk. - read more